Riya had spent weeks comparing lenders, gathering documents, and waiting for her loan application to be approved. When the approval message finally arrived, she assumed the hardest part was over.
A day passed. Then another. Her home seller wanted confirmation. Her contractor kept asking when the payment would arrive. Customer support only said, "Your loan is under process."
For borrowers, approval feels like the finish line. In reality, it is only one milestone in the loan disbursement process. Between sanction and funding lies a series of verification steps, document checks, compliance reviews, and operational workflows that can delay the transfer of funds.
For lenders, these delays are equally challenging. Every additional day increases customer anxiety, raises inbound support calls, and creates opportunities for borrowers to abandon the application or switch to another lender. An inefficient loan disbursement process doesn't just slow funding. It affects customer trust, operational costs, and business growth.
This article explores why the loan disbursement process often takes longer than expected, what commonly causes delays after loan approval, and how AI helps lenders keep borrowers informed and engaged until the funds are finally disbursed.
Simplify loan disbursement process with Callveriq
Understanding the Loan Disbursement Process
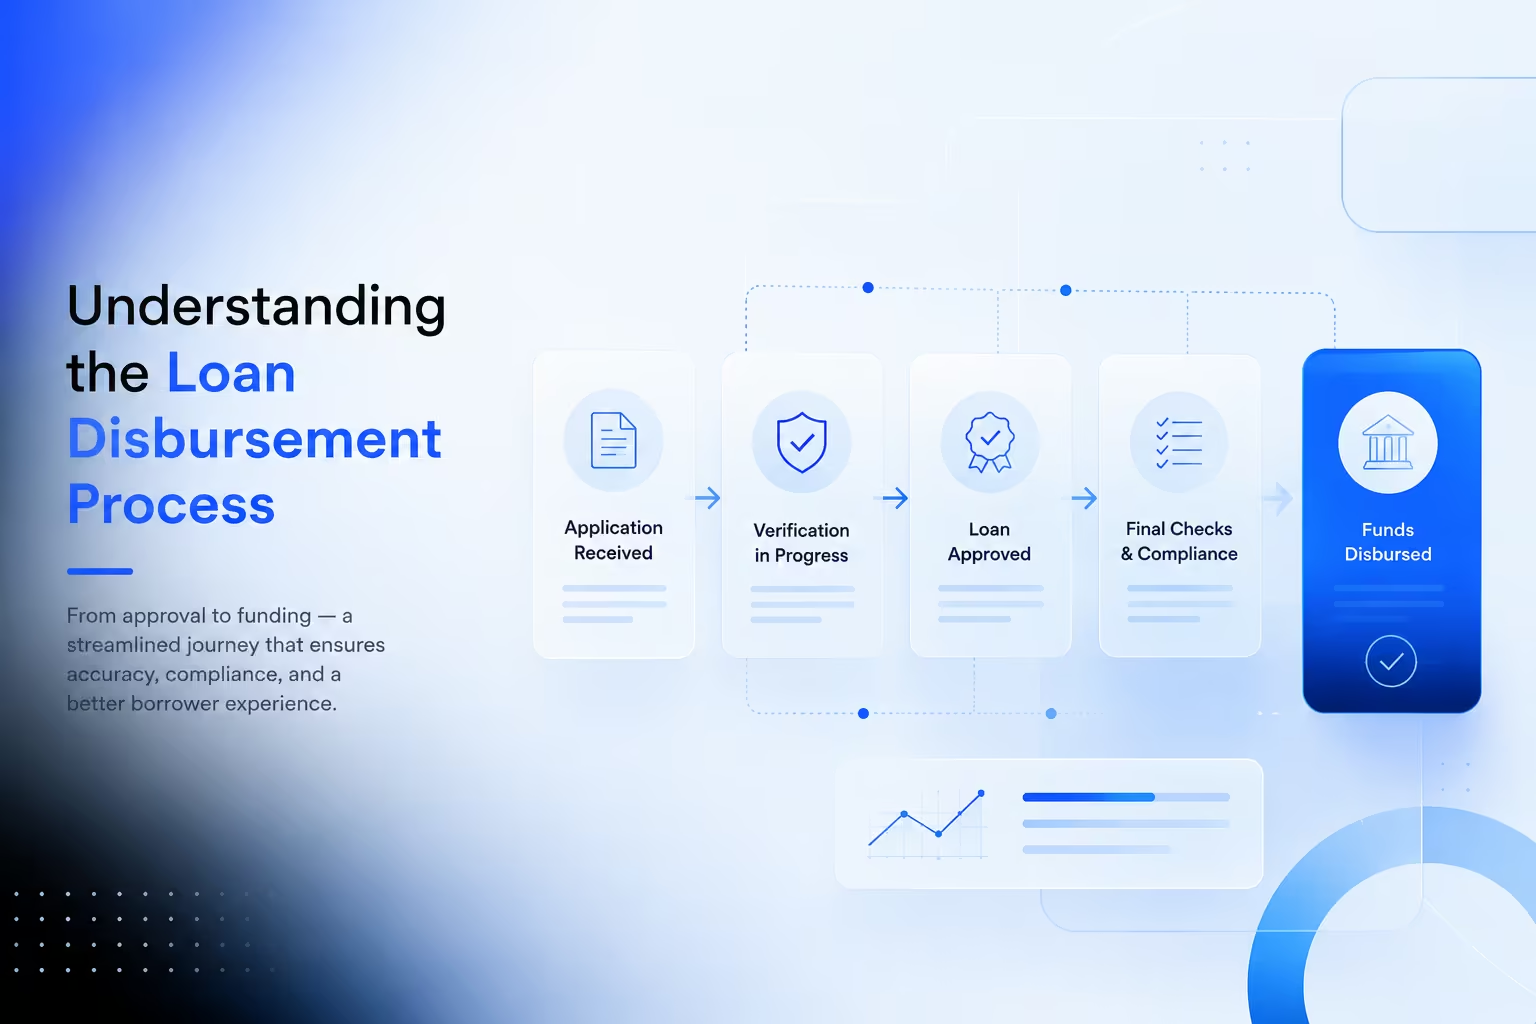
The loan disbursement process refers to everything that happens after a lender approves a loan and before the money reaches the borrower or the intended recipient.
While many borrowers think approval automatically triggers payment, lenders still need to complete several operational and regulatory checks before releasing funds.
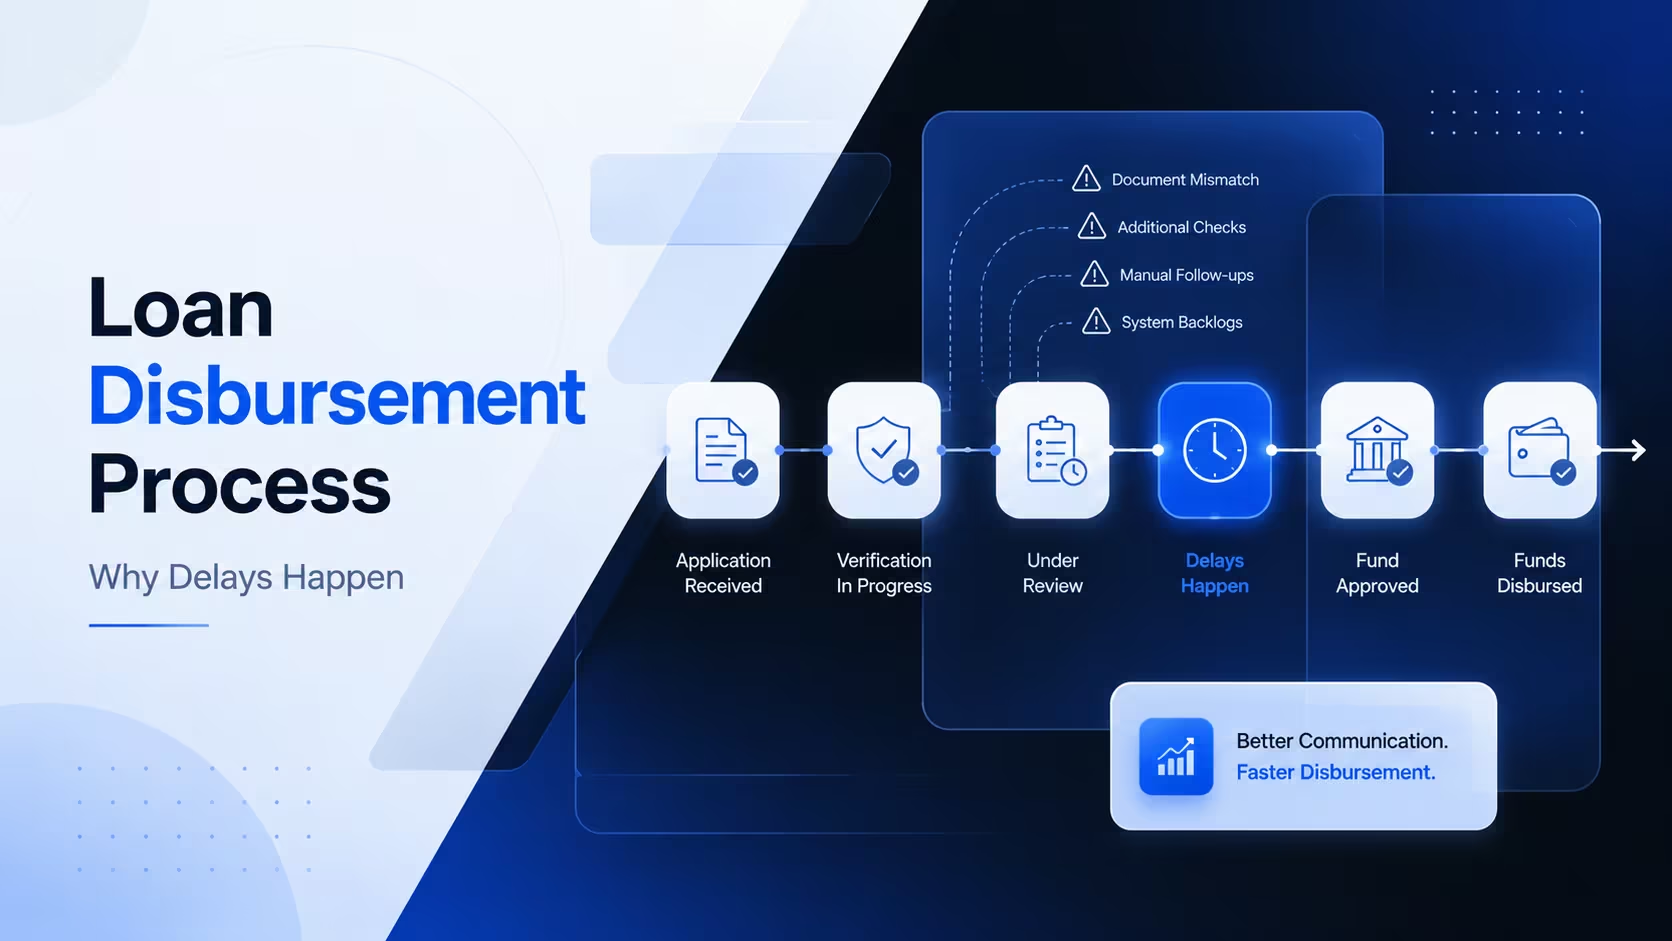
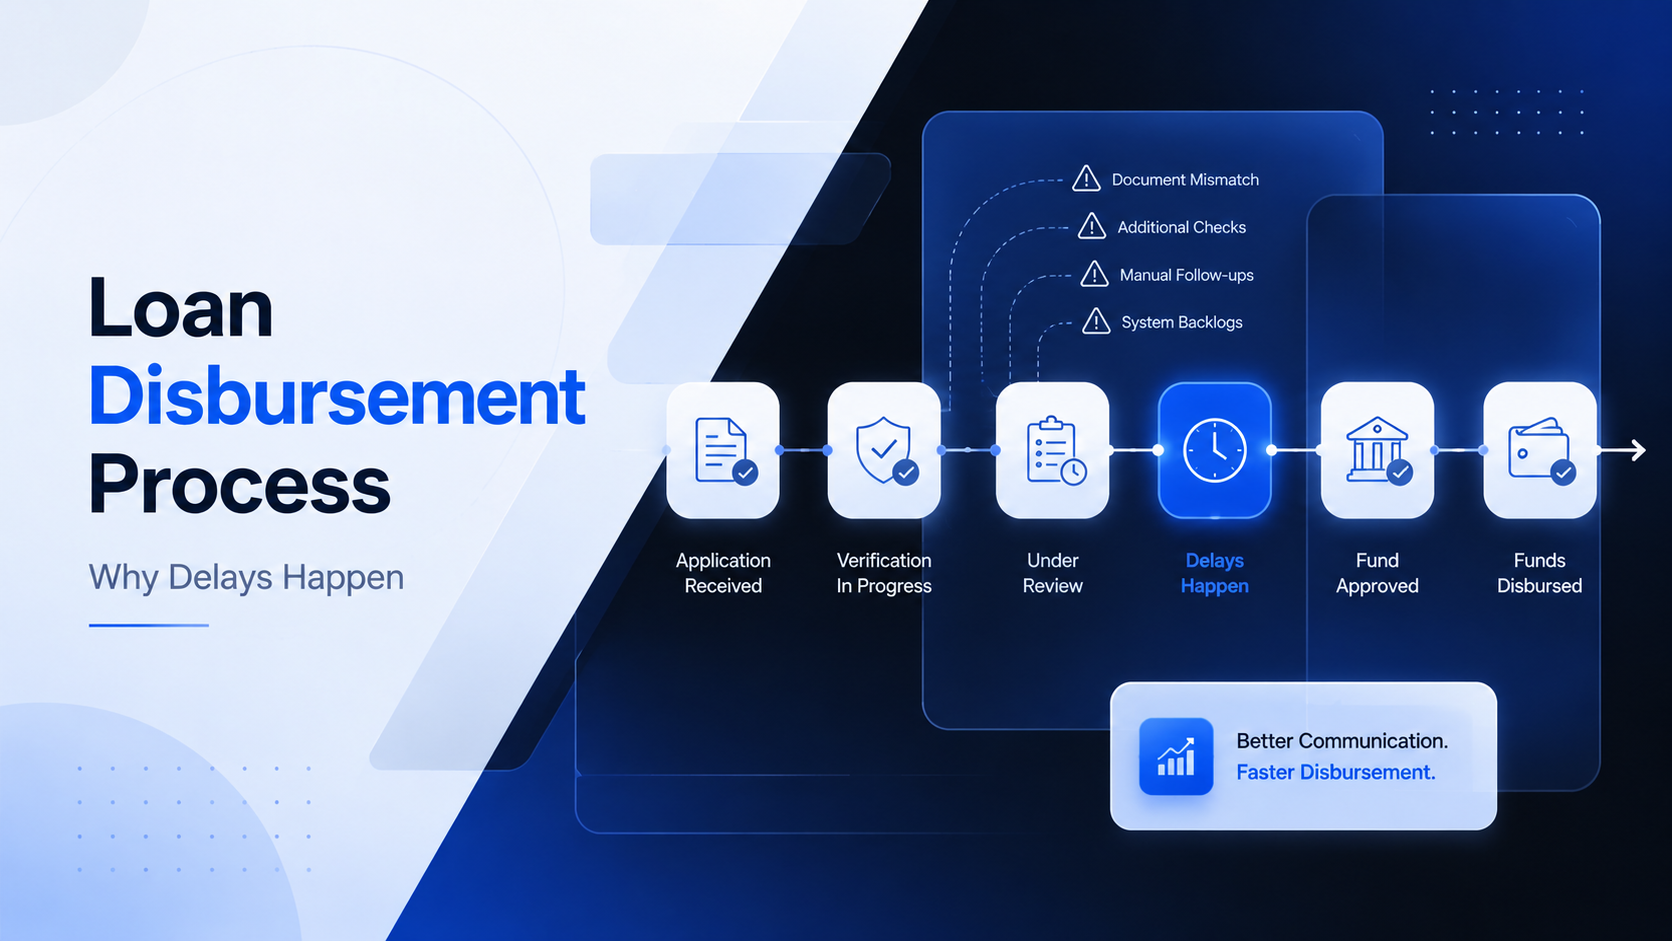
A typical loan disbursement process includes:
- Loan sanction and offer acceptance
- Final document verification
- Identity and compliance validation
- Agreement signing
- Bank account verification
- Internal approval workflows
- Payment authorization
- Fund transfer
Different loan products follow slightly different workflows.
For example:
- Personal loans often have faster digital disbursements.
- Home loans require property verification and legal approvals.
- Business loans may involve additional financial validation.
- Education loans frequently depend on institution verification before funds are released.
Every additional step makes the loan disbursement process more complex. While these checks protect both lenders and borrowers, they also create multiple points where delays can occur.
Why Borrowers Assume Approval Means Immediate Funding
Most digital experiences today are instant. Payments happen in seconds. Food arrives within minutes. Bank accounts open online.
Naturally, borrowers expect the same speed after loan approval.
However, lending remains a highly regulated industry. Financial institutions must verify compliance, prevent fraud, and ensure every loan meets internal and external requirements before money is released.
Without clear communication, borrowers interpret silence as uncertainty.
Questions begin piling up:
- Has my loan been rejected?
- Did I miss a document?
- When will the money arrive?
- Should I contact another lender?
These moments create unnecessary stress that often has little to do with the actual funding timeline.
Improve loan disbursement process with Callveriq
What Causes Delays in the Loan Disbursement Process After Sanction?
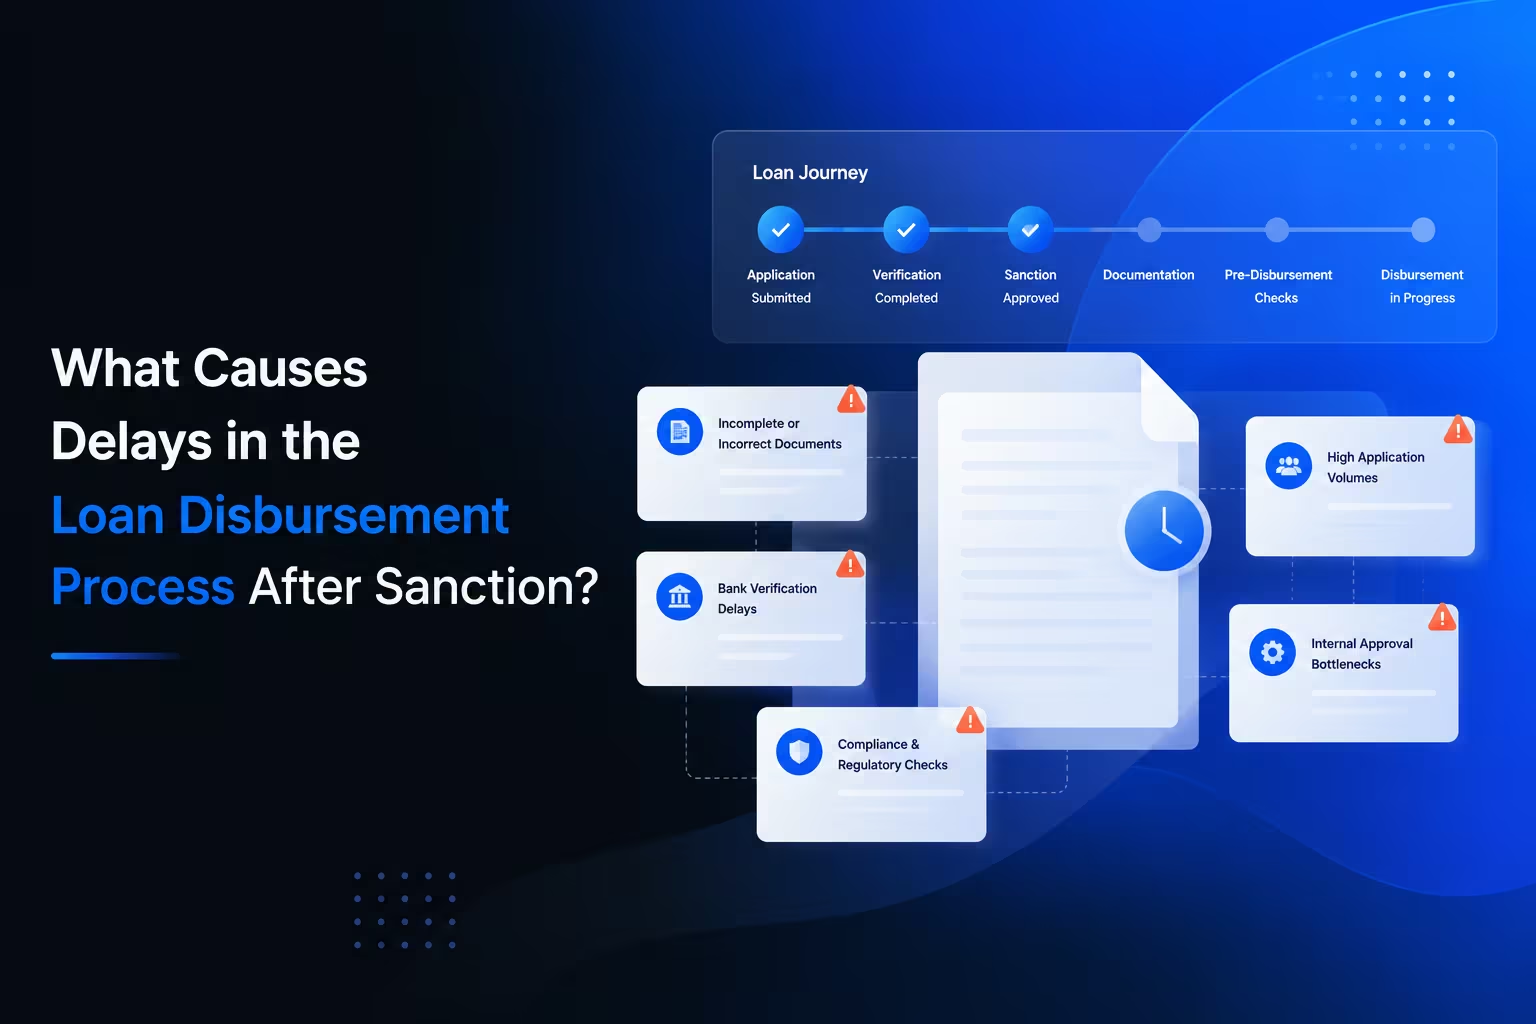
Receiving a sanction letter is an important milestone, but it is rarely the final step. Several operational factors can delay the loan disbursement process even after approval.
1. Missing or Incorrect Documentation
Documentation remains one of the biggest reasons for delayed disbursement. Borrowers often submit:
- Expired identity proofs
- Incomplete income documents
- Unsigned agreements
- Incorrect bank details
- Missing property documents
Each discrepancy requires manual follow-up, creating additional waiting time.
When borrowers do not realize a document is missing, the loan disbursement process can remain stalled for days without visible progress.
2. Internal Verification Workflows
Large lenders rarely rely on a single approval. Multiple departments may need to verify different aspects of the application. These include:
- Risk teams
- Operations
- Compliance
- Legal teams
- Finance
If even one approval remains pending, the entire loan disbursement process pauses.
3. Compliance and Regulatory Checks
Financial institutions operate under strict regulatory requirements. Before funds are released, lenders often complete:
- KYC validation
- AML screening
- Fraud detection
- Account verification
- Credit policy checks
These processes protect both the institution and borrowers but can extend timelines when exceptions are detected.
4. High Application Volumes
Seasonal demand also plays a major role. Periods like festive offers, educational admissions, housing seasons, or year-end business financing often lead to significantly higher loan applications.
Even with digital systems, operational teams can become overwhelmed. As workloads increase, the loan disbursement process naturally slows.
5. Manual Customer Communication
Ironically, communication itself can become a bottleneck.
Many lenders still depend on agents to:
- Request missing documents
- Explain next steps
- Schedule verification
- Answer borrower queries
This manual approach creates delays because every interaction depends on agent availability.
Meanwhile, borrowers continue waiting without updates.
The Hidden Cost of Delays
A delayed loan disbursement process affects far more than customer satisfaction.
For borrowers, delays may result in:
- Lost property deals
- Missed admission deadlines
- Supplier payment issues
- Increased financial stress
For lenders, delays often mean:
- Higher support costs
- More follow-up calls
- Lower customer trust
- Increased application abandonment
- Reduced referral rates
What appears to be a simple operational delay often impacts the entire customer experience.
Callveriq improves your loan disbursement process
This blog is just the start.
Unlock the power of Callveriq’s AI with a live demo.
How Can Lenders Keep Borrowers Engaged Between Approval and Disbursal?
One of the biggest mistakes lenders make is assuming borrowers will patiently wait.
In reality, silence creates doubt. Even when the loan disbursement process is progressing exactly as planned, borrowers who receive no updates often believe something has gone wrong. This uncertainty increases support calls, escalations, and drop-offs.
Keeping borrowers engaged doesn't always require speeding up disbursement. Often, it requires improving communication.
1. Provide Real-Time Status Updates
Borrowers don't necessarily expect instant funding. They expect visibility.
Instead of leaving applicants wondering about the next step, lenders can proactively share updates such as:
- Documents received
- Verification completed
- Compliance checks in progress
- Payment approved
- Expected disbursement timeline
Simple updates reduce anxiety while creating transparency throughout the loan disbursement process.
2. Send Personalized Reminders
Missing documents are one of the easiest delays to prevent.
Rather than waiting for customers to call support, lenders can automatically remind borrowers about:
- Pending signatures
- Expiring documents
- Bank account verification
- Additional paperwork
Personalized reminders help borrowers act faster, preventing unnecessary delays in the loan disbursement process.
3. Educate Borrowers About the Journey
Many customers simply don't know what happens after approval.
Short educational messages explaining the remaining steps can significantly improve trust.
For example: "Your loan has been approved. We are currently verifying your bank account before releasing funds."
This single message reassures borrowers that progress is being made. Without context, even a one-day delay can feel like an indefinite wait.
4. Use Multiple Communication Channels
Borrowers have different communication preferences. Some respond quickly to WhatsApp. Others check SMS more frequently.
Some prefer phone calls. Using an omnichannel approach ensures borrowers receive timely updates regardless of their preferred channel.
The result is a smoother loan disbursement process with fewer missed communications and better customer engagement.
Improve loan disbursement process with Callveriq.
What Documents Most Often Hold Up Loan Disbursement?
For many borrowers, the paperwork feels complete once they upload a few identity documents. Behind the scenes, however, lenders often require multiple rounds of validation before the loan disbursement process can move forward.
Even a small discrepancy can pause the workflow, requiring manual intervention from operations teams and follow-up with the borrower.
1. Identity and KYC Documents
The most common delays occur during Know Your Customer (KYC) verification. Expired identity proofs, mismatched names, incorrect addresses, or blurry document uploads often trigger additional reviews.
For digital lenders processing thousands of applications daily, these exceptions quickly accumulate and extend the loan disbursement process.
2. Income and Employment Proof
Lenders need confidence that borrowers can repay the loan. Missing salary slips, outdated bank statements, inconsistent income records, or unverifiable employment details frequently delay approvals that have already been sanctioned.
In business lending, incomplete GST records, financial statements, or tax filings can add another layer of verification before funds are released.
3. Bank Account Verification
Even after a loan is approved, lenders must ensure the funds reach the correct account.
Incorrect account numbers, mismatched beneficiary names, inactive accounts, or failed penny-drop verification often force lenders to repeat the validation process, delaying the loan approval and disbursement journey.
4. Property and Asset Documents
For secured loans such as home or vehicle financing, additional documentation is usually required. These may include:
- Property ownership records
- Sale agreements
- Builder approvals
- Insurance documents
- Vehicle registration details
Because several third parties are involved, even one missing document can extend the loan disbursement process by days or weeks.
5. Signed Agreements
Digital lending has reduced paperwork considerably, but borrowers still need to complete consent forms, loan agreements, e-signatures, and mandate authorizations. Applications often remain pending simply because borrowers overlook an email requesting their signature. Without proactive reminders, these applications quietly sit in the queue, increasing operational effort for lenders.
Automate loan disbursement process follow-ups
How AI Reduces Drop-Offs Before Funds Are Disbursed
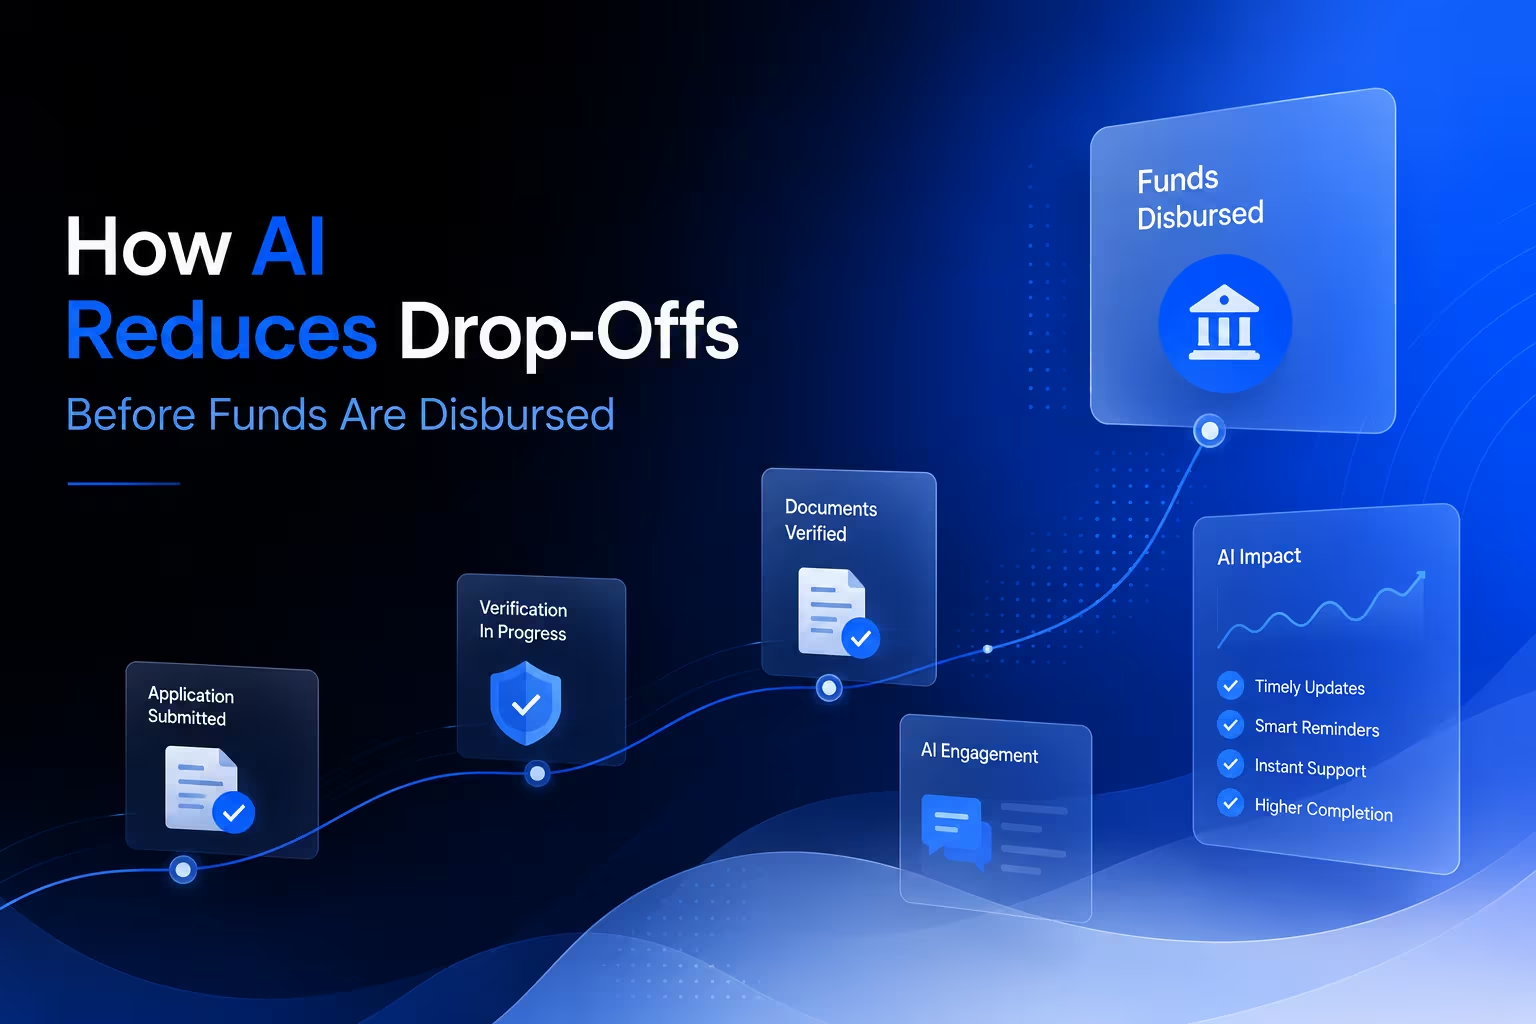
Borrowers rarely abandon a loan because they dislike receiving money. They leave because uncertainty makes them lose confidence.
When communication stops, borrowers begin exploring alternatives, repeatedly contact customer support, or assume their application has been rejected. AI helps bridge this communication gap without requiring large support teams.
1. AI Delivers Instant Progress Updates
Modern lenders process thousands of applications simultaneously. Keeping every borrower informed manually is nearly impossible. AI can automatically notify borrowers whenever their application reaches a new milestone.
Instead of hearing nothing for several days, borrowers receive updates like:
- Your documents have been verified.
- Your bank account validation is complete.
- Your loan is awaiting final authorization.
- Funds are expected to be transferred shortly.
These proactive updates make the loan disbursement process feel transparent rather than uncertain.
2. AI Identifies Potential Delays Early
Not every application follows the same path. Some borrowers submit incomplete documents. Others delay signing agreements or fail verification checks.
AI systems can identify these bottlenecks early and trigger personalized nudges before they become larger problems.
For example, instead of waiting for a support executive to review a queue, AI can immediately notify a borrower about a missing document and provide instructions for completing the next step. This significantly reduces loan disbursement delays while improving the borrower experience.
3. AI Answers Borrower Questions Around the Clock
One of the biggest drivers of support volume is a simple question:
"When will I receive my loan?"
AI-powered voice agents and conversational assistants can answer these questions instantly by accessing real-time application status. Borrowers no longer have to wait on hold or send repeated emails to receive basic updates.
Support teams, meanwhile, can focus on resolving complex cases rather than answering repetitive queries.
4. AI Personalizes Every Conversation
Borrowers are not all at the same stage. Some are waiting for verification. Others have completed every step and are simply awaiting payment.
AI personalizes communication based on each applicant's status, ensuring every message is timely and relevant. Rather than sending generic notifications, lenders can create meaningful conversations that increase trust throughout the digital loan disbursement journey.
5. AI Creates Consistency Across Channels
Today's borrowers expect flexibility. They may begin their application online, upload documents through WhatsApp, receive approval via email, and ask questions over a phone call.
AI ensures these interactions remain connected. Regardless of the communication channel, borrowers receive consistent information without repeating their questions or explaining their application history multiple times.
This creates a far smoother AI loan disbursement process, where communication feels continuous rather than fragmented.
Improve loan disbursement process with Callveriq.
Best Practices for Building a Faster Loan Disbursement Process
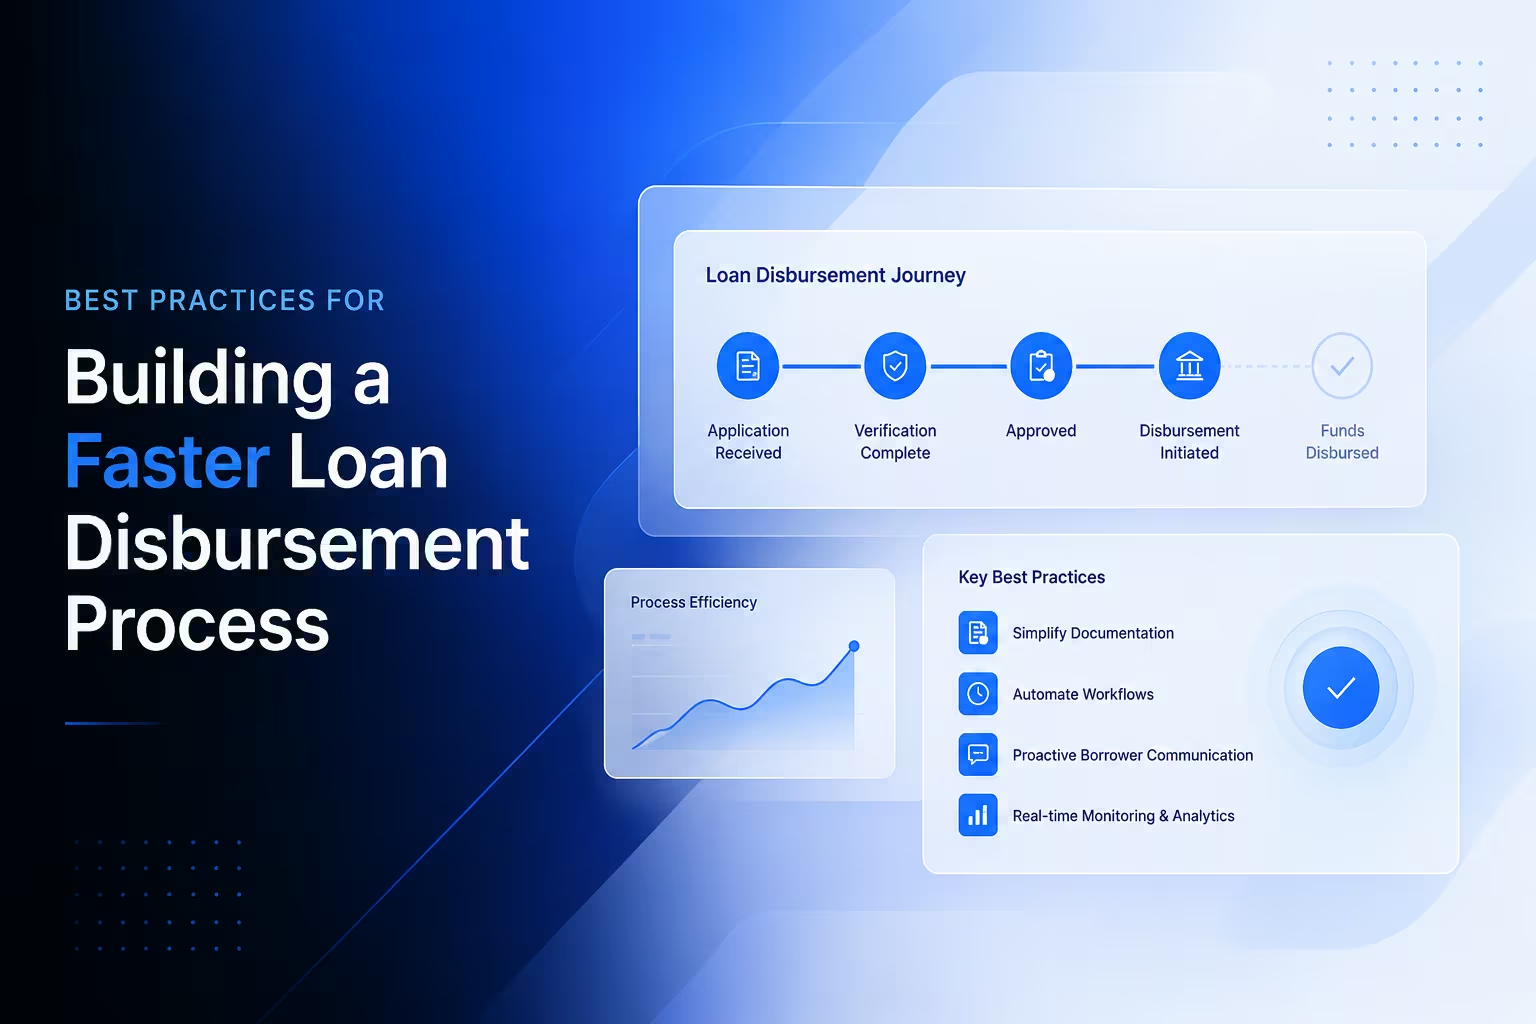
While regulations and compliance checks cannot be eliminated, lenders can redesign their operations to reduce unnecessary friction. The most successful lending organizations focus on creating visibility rather than simply increasing speed.
They simplify documentation requirements by clearly communicating every required document before approval. They digitize verification workflows wherever possible, reducing manual effort and minimizing repetitive reviews. Automation also plays an important role. Borrowers should never have to wonder whether their documents were received or what happens next. Automated status updates, intelligent reminders, and AI-powered borrower assistance keep customers engaged without overwhelming support teams.
Equally important is measuring where delays actually occur. Instead of assuming the loan disbursement process is slow from start to finish, lenders can analyze each stage individually. They often discover that a handful of recurring bottlenecks account for the majority of delays. Improving these specific stages creates a more efficient experience without requiring a complete operational overhaul.
Streamline loan disbursement process using Callveriq
What This Means For Loan Disbursement Process
The moment a borrower receives loan approval should be the beginning of confidence, not uncertainty. Yet for many applicants, the period between sanction and funding becomes the most stressful part of the journey. Missing documents, manual verification, compliance checks, and fragmented communication often slow the loan disbursement process, leaving borrowers anxious and lenders overwhelmed with support requests.
While some delays are unavoidable, poor communication is not. Keeping borrowers informed at every stage builds trust, reduces unnecessary follow-ups, and prevents applicants from abandoning their journey before the funds are released. AI makes this possible by delivering proactive updates, identifying bottlenecks early, automating reminders, and providing instant answers across every customer touchpoint.
As lending continues to become more digital, the institutions that stand out won't simply be the ones with the fastest approvals. They'll be the ones that make the entire loan disbursement process feel transparent, predictable, and reassuring from start to finish. By combining operational efficiency with intelligent borrower engagement, lenders can create experiences that inspire confidence long before the funds reach a customer's account.
Callveriq simplifies loan disbursement process. Book your demo!
FAQs
1. How long does the loan disbursement process usually take?
The loan disbursement process can take anywhere from a few hours to several days, depending on the lender, loan type, and document verification requirements.
2. Can the loan disbursement process be tracked online?
Yes. Many lenders allow borrowers to track the loan disbursement process through their website, mobile app, or automated SMS and email notifications.
3. Does the loan disbursement process differ for secured and unsecured loans?
Yes. The loan disbursement process for secured loans typically includes additional legal and asset verification, while unsecured loans generally have fewer verification steps.
4. Can weekends or public holidays affect the loan disbursement process?
Yes. Banking holidays and non-working days may delay the loan disbursement process, especially if fund transfers or final approvals depend on banking operations.
5. What should borrowers do if the loan disbursement process takes longer than expected?
If the loan disbursement process exceeds the estimated timeline, borrowers should check their application status, verify that all required documents have been submitted, and contact their lender for an update.